Drop in the OM, the T-12, the rent roll. RVP Underwriter normalizes the seller's numbers, exposes the red flags, and returns a defensible offer, with the receipts to back it up.
From a folder of broker PDFs to a defensible offer, start to finish. Want the full walkthrough, every report opened and explained? Watch the full walk-through →
Brokers inflate income. Expenses conveniently forget management, reserves, and the reassessment coming next January. Cap rates get computed off a pro-forma that doesn't exist yet. And every serious deal takes hours in a spreadsheet before you know if it's worth your time.
RVP Underwriter reads the documents the way a senior underwriter would. It normalizes the numbers, cross-checks the rent roll against the T-12, researches the local market live, and returns a verdict you can defend to a partner or a lender, in about a minute.
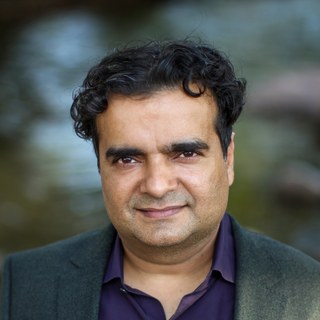
Built by Ajay "AJ" Kuckreja, a Fortune 500 executive and real estate investor with 20+ years of experience, who has owned, operated, and exited an RV park. Not a software company guessing at the numbers.
The OM, a T-12, a rent roll, up to ten files, even a zip. Desktop or phone. No forms and no data entry, ever.
NOI, cap rate, DSCR, cash-on-cash, and price per site as presented, plus a count of the red flags it already sees. Free.
Normalized NOI with receipts, live market research, expense benchmarks, stress tests, and three ready offer structures.
A GO / NO-GO verdict, a drafted LOI, a lender-ready memo, and a checklist of documents to request next.
Drop in whatever you have. OM, T-12, rent roll, up to ten files, even a zip. Desktop or phone. No forms, no data entry, ever.
The five numbers that matter. NOI, cap rate, DSCR, cash-on-cash, price per site, as presented, plus a count of red flags. Free, no account required.
Normalized NOI, with receipts. Every adjustment shown line by line with the reasoning, so you can defend the figure to a partner or a lender.
Income never gets inflated. Rent roll and T-12 are cross-checked; stated occupancy has to earn its way into the math with evidence.
Live research on every deal. Today's debt market, county tax reassessment habits, insurance trends, market cap rates, local demand drivers. Researched fresh, not looked up in a stale table.
An expense benchmarker that flags padded lines and catches the missing ones: management, reserves, the usual suspects.
A second reviewer audits the work. An independent AI pass checks every adjustment before you see it, the way a senior underwriter checks an analyst.
Judgment calls are disclosed, not hidden. The decisions that moved the numbers, how confident it is in each, and which document would settle it.
Risks and red flags for THIS property. Researched for the specific park and county, ranked by severity. Not a generic checklist.
A plain-English deal brief up top, so you understand the story before you touch the spreadsheet.
Three ready offer structures. Conventional, bank plus seller second, and full seller carry. Each with the maximum price that still hits your targets, with DSCR and cash-on-cash shown.
It reads for seller-financing signals in the documents and structures around them when they are there.
A clear GO / NO-GO verdict with the recommended structure and why.
It never shrugs. Overpriced listings get the price that actually pencils. Unpriced listings get valued from income. You always leave with an offer you can send.
Stress tests before life runs them for you. Rate jumps, empty sites, tax reassessment, each with the DSCR it leaves behind.
A hidden-upside finder. Income the listing never mentions (utility bill-backs, below-market rents, ancillary revenue), quantified in annual NOI and value created.
Your targets, not ours. Set your own DSCR, cash-on-cash, and cost of capital. Every verdict and MAO honors them.
Talk to the underwriter. Ask why it made any adjustment, or tell it to change the numbers. "What if I get it at $2.2M with 20% down?" re-runs instantly.
A next-requests checklist. Exactly which documents to demand from the broker before you go further.
A one-pager PDF with the whole deal on a single page, ready to forward.
The full underwriting report. Every number, adjustment, offer, and stress test, as a PDF or phone-friendly HTML.
A Letter of Intent drafted and ready to send, with guidance tailored to who is selling: listed, off-market, or FSBO.
A lender-ready deal memo that speaks bank. Conventional first lien, DSCR math, risk mitigants. Your seller-carry strategy never appears in it, by design.
An investor pitch deck (PowerPoint) for raising partners on the deal.
The live Excel model. Every formula open to tweak, every normalization color-coded, plus a 10-year pro-forma with refinance, exit, and investor IRR.
A private negotiation playbook built from this deal: scripts for this seller, your leverage points, and your walk-away number. The one document you never forward.
Your brand on everything. Logo, colors, and fonts on the documents, and on the platform itself.
A deal pipeline that saves every deal and picks it back up the moment new documents arrive.
The underwriting report shows every adjustment line by line: the seller's figure, the normalized figure, the reason, and the confidence. Bring it to a partner. Bring it to a lender. Bring it to the broker.
"It caught a $38k tax reassessment the broker forgot to mention. That single line changed the offer."
Instant deal checks are free and unlimited with no account. Your first full underwrites are free with a free account, no card. Current plans and limits are kept in one place so they are never out of date here.
About a minute for the five headline numbers, and typically under three minutes for the full report, including the live market research pass.
Whatever you have. OM, T-12, rent roll, any subset works. The more you provide, the tighter the normalization. It even reads a zip.
No. Everything the tool produces is a starting point for your own due diligence, not investment advice.
It's researched live, per deal, per county: debt market, tax reassessment habits, insurance trends, market cap rates. Not a stale table.
Because it counts the costs the seller's books leave out: a management fee even if they self-manage, a capital reserve, realistic repairs, verified occupancy instead of the peak-season figure, and the property-tax bill you'd actually pay. Every adjusted line is shown with a plain-English reason, and an independent second AI pass audits the work before you see it. You verify rather than trust.
Your documents are processed to produce your analysis and are never shared or used for anything else. Saved deals live in your account, and everything sent to a lender or investor carries your identity, never ours.
Yes. Set your own DSCR, cash-on-cash, and cost of capital. Ask the underwriter to re-run at a different price or leverage, and it re-runs instantly.
Drop in the OM. Unlimited instant checks, your first 5 full underwrites free, no credit card to start.
 RVP Underwriter